Inside IR35 Mortgage: How It Affects Your Borrowing Capacity (2026 Guide)
Applying for an inside IR35 mortgage directly affects how UK lenders calculate your borrowing capacity, rather than your eligibility. High-street lenders assess net umbrella payslip income after statutory employment deductions. Conversely, specialist lenders assessing an inside IR35 mortgage annualise gross contract day rates, which can significantly increase borrowing power. All applications remain subject to underwriting and status.
Table of Contents
- How Do UK Lenders Assess an Inside IR35 Mortgage?
- Why Does Umbrella Net Pay Reduce Inside IR35 Mortgage Borrowing Capacity?
- How Does Day-Rate Underwriting Work for an Inside IR35 Mortgage?
- Comparison: Umbrella Payslip vs Day-Rate Multiplier Routes
- What Documents Are Required for an Inside IR35 Mortgage Application?
- Can Gaps Between Contracts Affect an Inside IR35 Mortgage?
- Frequently Asked Questions
How Do UK Lenders Assess an Inside IR35 Mortgage?
Securing an inside IR35 mortgage involves navigating how your earnings are paid and evidenced, rather than proving whether you qualify. In the UK, mortgage providers evaluate inside-IR35 applicants through one of two distinct routes: standard employment payslip assessment or specialist contract-based underwriting.
The HMRC off-payroll working rules on GOV.UK establish tax status and deemed employment for contractors. However, HMRC rules do not dictate how mortgage underwriters determine affordability. The Prudential Regulation Authority (PRA) and the FCA MCOB responsible lending standards require providers to ensure borrowing is sustainable, leaving specific calculation models to individual lender criteria.
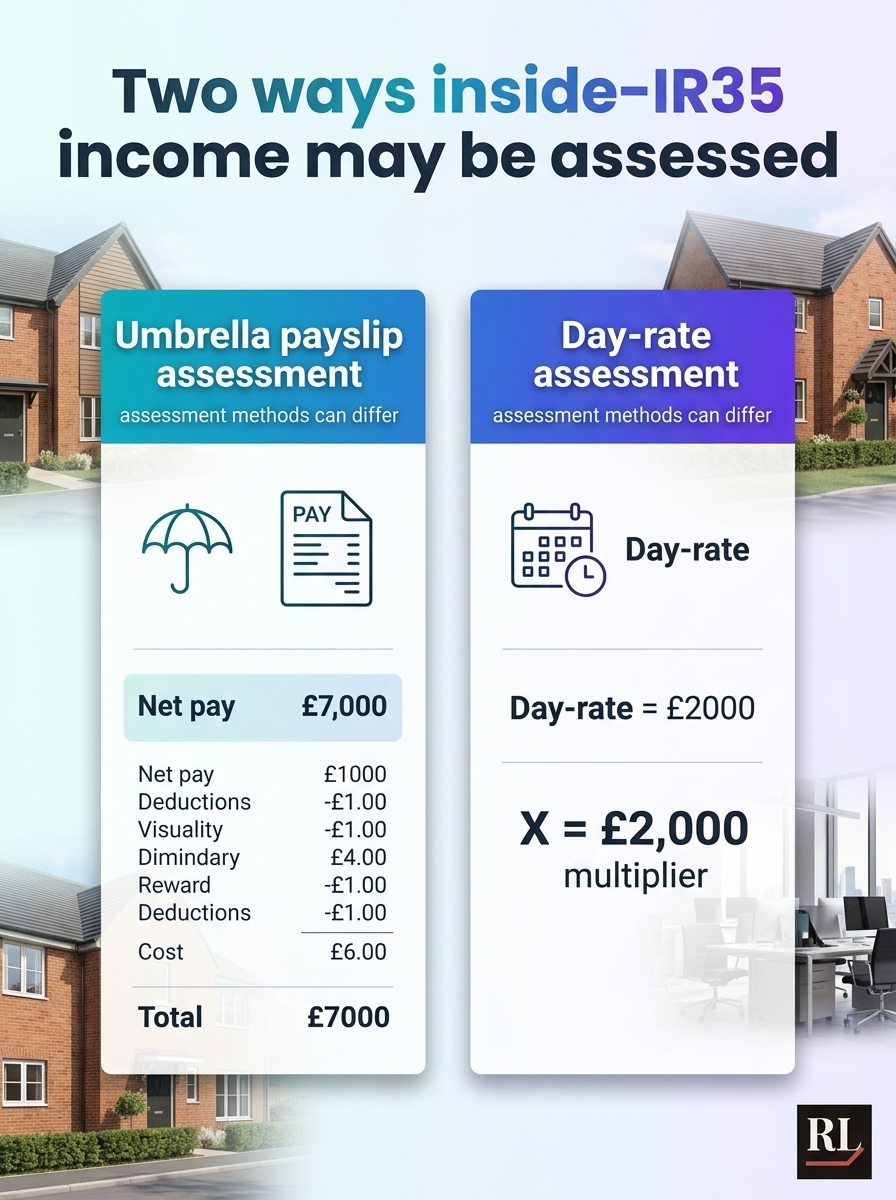
Mainstream high-street lenders typically treat you as a fixed-term employee or agency worker. They assess the net pay figures reported on umbrella payslips. Because umbrella deductions reduce your visible net salary, this route frequently leads to a compressed borrowing figure.
By contrast, specialist contractor lenders evaluate your application as an independent professional. They look past the payroll mechanics to calculate an inside IR35 mortgage using the gross contract assignment value. For further context on contract criteria, see our dedicated guide to IR35 contractor mortgages.
Why Does Umbrella Net Pay Reduce Inside IR35 Mortgage Borrowing Capacity?
When working through an umbrella company, your top-line invoice amount is the assignment rate. Crucially, this rate does not represent pure personal salary.
Before your taxable pay is calculated, statutory employer costs are deducted from the assignment rate. These include Employer National Insurance Contributions (NICs), the Apprenticeship Levy, and the umbrella margin fee. Only after these deductions are made are employee NICs, PAYE income tax, and pension contributions subtracted from your taxable pay.
High-street mortgage calculators input the net or basic taxable pay shown on umbrella payslips. They do not recognise that the contract rate was structured to absorb employment overheads. Consequently, an inside IR35 mortgage assessed on the high street is calculated against an artificially suppressed baseline.
To understand how umbrella deductions are treated by underwriters, consult our umbrella company mortgage FAQ.
How Does Day-Rate Underwriting Work for an Inside IR35 Mortgage?
Specialist contractor underwriting determines your inside IR35 mortgage borrowing capacity using the top-line gross contract rate rather than net payslips. Lenders in this sector convert your agreed day rate into an annualised gross income figure.
The established industry formula takes your day rate, multiplies it by the contracted days per week (typically five), and then multiplies by a standard working year, commonly 46 or 48 weeks. This standard deduction builds in allowance for unpaid annual leave and expected gaps between projects.
For example, a contractor earning £500 per day over five days per week across 46 weeks is assessed as having an annualised gross income of £115,000. Specialist lenders apply standard borrowing multiples (typically 4.5 times income) directly to this gross figure, subject to credit score and personal liabilities.
This underwriting methodology ensures your genuine earning capability is reflected when applying for an inside IR35 mortgage. You can explore contractor affordability mechanics in our contractor mortgage guide and our day-rate contractor FAQ.
Comparison: Umbrella Payslip vs Day-Rate Multiplier Routes
| Assessment Factor | High-Street Umbrella Route | Specialist Day-Rate Multiplier Route |
|---|---|---|
| Income Baseline | Net or basic taxable pay from umbrella payslips. | Gross contract day rate annualised across 46–48 weeks. |
| Borrowing Capacity Impact | Compressed borrowing limit due to employer taxes and fees. | Substantially higher borrowing power reflecting gross earnings. |
| Contract Requirements | Standard employment proof; contract may be treated as fixed-term. | Formal contract showing day rate and minimum remaining term. |
| Track Record Needed | Typically 3 to 6 months of continuous payslips. | Usually 12 to 24 months of continuous contracting history. |
What Documents Are Required for an Inside IR35 Mortgage Application?
Packaging an inside IR35 mortgage application requires clear documentation reconciling both your contractual terms and payroll receipts. Thorough evidence preparation prevents underwriting delays.
To qualify for a day-rate calculation, you must provide your current signed contract detailing the day rate, start date, and contracted hours. If the assignment has under six weeks remaining, an extension letter or email confirmation from your end client or agency is generally necessary.
Specialist lenders will also request your last three months of consecutive umbrella payslips together with matching bank statements. This allows underwriters to verify that contract billing aligns with actual deposits.
If you recently switched from an outside-IR35 limited company to an inside-IR35 assignment, submit your previous company accounts and SA302 calculations. This documents uninterrupted career continuity in your sector.
Can Gaps Between Contracts Affect an Inside IR35 Mortgage?
Contract continuity is a primary consideration for underwriters assessing an inside IR35 mortgage. Planned gaps between contracts for holidays or professional development are standard practice and widely accepted within limits.
Most specialist mortgage lenders comfortably accommodate assignment gaps of up to four to six weeks. For gaps exceeding eight weeks, underwriters examine your broader sector experience, accumulated savings reserves, and ongoing market demand for your skillset.
A proven track record of twelve to twenty-four months in contracting reassures lenders that gaps are voluntary. Applying while an active contract is in place ensures the strongest borrowing assessment.
Frequently Asked Questions
Does changing from outside to inside IR35 affect a remortgage?
Switching from an outside IR35 limited company to an inside IR35 umbrella contract changes the documentary evidence required. A straightforward product transfer with your existing lender rarely triggers fresh affordability checks. However, remortgaging to a new lender or raising extra capital requires a full reassessment based on current contract or umbrella terms.
Can umbrella company pension contributions reduce mortgage borrowing?
Salary-sacrifice pension contributions reduce the taxable net pay displayed on umbrella payslips. On high-street affordability models, this lower net income directly restricts borrowing. Specialist lenders assessing an inside IR35 mortgage calculate affordability before pension deductions, protecting your borrowing capacity.
How soon after starting an inside IR35 contract can I apply?
Specialist lenders can consider an inside IR35 mortgage application immediately upon signing a new contract, provided you have at least twelve months of continuous contracting history in the same profession. High-street lenders typically require a minimum of three consecutive months of umbrella payslips before considering an application.
Can a joint applicant’s salary be combined with inside IR35 day-rate income?
Yes. Specialist lenders regularly assess joint applications where one borrower is an inside IR35 contractor and the other is an employed or self-employed earner. The contractor’s day rate is annualised, the secondary applicant’s verified income is added, and household commitments are subtracted to determine joint borrowing capacity.
YOUR HOME MAY BE REPOSSESSED IF YOU DO NOT KEEP UP REPAYMENTS ON YOUR MORTGAGE.
The guides and articles on this website are provided for general information only. They are not tailored to your personal circumstances and should not be treated as financial advice or a personal recommendation. If you would like advice based on your individual circumstances, please speak to an adviser.
Mortgage advice is provided by Hayden Richards, CeMAP-qualified, as a Registered Individual of Marklay Mortgages Ltd, which is authorised and regulated by the Financial Conduct Authority (FRN 930490). Richards & Logic is a trading style of MarketMedia Ltd (registered in England and Wales, 07765565).